Crypto Gains Tracker
Track digital asset profits • 2026 markets
Crypto Gains Formula:
Show the calculatorProfit/Loss = (Current Price - Purchase Price) × Quantity
Where:
- Current Price: Current market value of asset
- Purchase Price: Original acquisition cost
- Quantity: Amount of cryptocurrency owned
This formula calculates the unrealized gains or losses for a crypto position. For realized gains (sold positions), use the selling price instead of current price. This forms the basis for tax reporting and portfolio performance tracking.
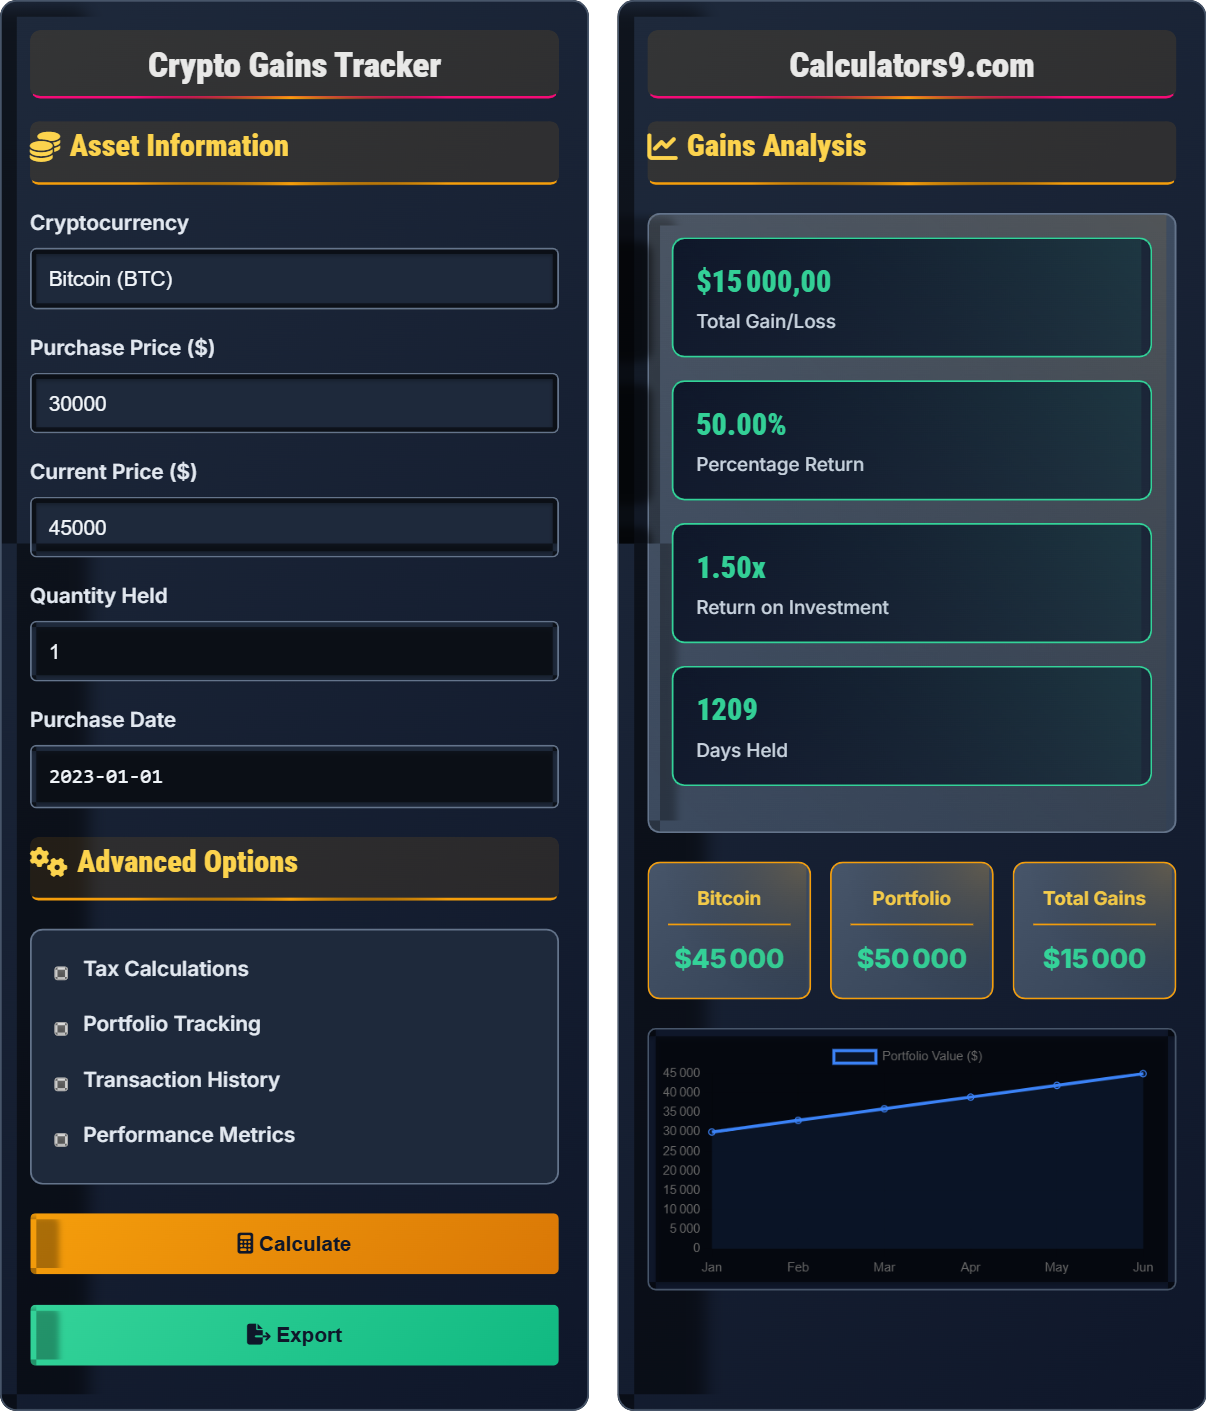
Example: Bought 1 BTC at $30,000, now worth $45,000:
Profit = ($45,000 - $30,000) × 1 = $15,000
Therefore, the unrealized gain is $15,000, representing a 50% return on investment.
Asset Information
Advanced Options
Gains Analysis
Gain/Loss Breakdown
Tax Implications
Portfolio Distribution
HODL Strategy
Comprehensive Crypto Gains Guide
Crypto gains tracking involves monitoring the profit or loss from cryptocurrency investments. This includes both unrealized gains (paper profits/losses) and realized gains (actual profits/losses from sold positions). Proper tracking is essential for tax compliance, portfolio management, and strategic decision-making.
The standard crypto gains calculation uses the following formula:
Where:
- Current Price = Current market value of the asset
- Purchase Price = Original acquisition cost
- Quantity = Amount of cryptocurrency owned
Various methods exist for tracking crypto gains:
- Manual Tracking: Spreadsheets and records
- Exchange Tools: Built-in portfolio tracking
- Third-Party Apps: Specialized crypto tracking software
- Hardware Wallets: Connected tracking solutions
- Record Keeping: Maintain detailed transaction history
- Regular Updates: Update portfolio values regularly
- Tax Preparation: Prepare for tax season throughout the year
- Security: Protect sensitive financial data
- Diversification: Track across multiple assets and exchanges
Crypto Gains Fundamentals
Monitoring profit/loss from cryptocurrency investments.
Gains = (Current Price - Purchase Price) × Quantity
Where gains = profit/loss, current price = market value, purchase price = cost basis, quantity = holdings.
- Track realized vs unrealized gains
- Consider tax implications
- Maintain accurate records
Tax & Compliance
Required for realized gains and losses.
- Keep detailed transaction records
- Calculate cost basis accurately
- Report gains/losses annually
- Consult tax professionals
- Every trade is a taxable event
- Gifts and donations have tax implications
- Staking rewards are taxable income
- Record keeping is essential for audits
Crypto Gains Learning Quiz
How are cryptocurrencies classified for tax purposes in most jurisdictions?
The answer is B) Property. In most jurisdictions, including the US, cryptocurrencies are treated as property for tax purposes, not currency. This means transactions involving crypto are subject to capital gains tax rules, and each sale or exchange is a taxable event.
Understanding the tax classification of cryptocurrencies is crucial for compliance. Because they're treated as property, you must track the cost basis and holding period for each transaction. This classification affects how gains are calculated, the applicable tax rates, and the documentation required for tax reporting.
Tax Classification: How assets are categorized for taxation
Property Treatment: Subject to capital gains tax
Taxable Event: Transaction triggering tax liability• Crypto treated as property, not currency
• Each trade is a taxable event
• Cost basis tracking is required
• Remember: Property = Capital Gains treatment
• Keep detailed records of all transactions
• Use crypto tax software for complex portfolios
• Treating crypto as currency for tax purposes
• Not tracking cost basis for purchases
• Forgetting to report small transactions
If you bought 2 ETH at $2,000 each and they're now worth $3,500 each, what are your unrealized gains? Show your work.
Step 1: Calculate total purchase cost = Quantity × Purchase Price
Total Purchase = 2 × $2,000 = $4,000
Step 2: Calculate total current value = Quantity × Current Price
Total Current = 2 × $3,500 = $7,000
Step 3: Calculate unrealized gains = Current Value - Purchase Cost
Unrealized Gains = $7,000 - $4,000 = $3,000
Therefore, your unrealized gains are $3,000.
This calculation demonstrates the basic formula for unrealized crypto gains. The key is to multiply the quantity by both purchase and current prices separately, then find the difference. This gives you the paper profit/loss that exists until you sell the assets. Remember that taxes are only due on realized gains (when sold).
Unrealized Gains: Paper profits/losses (not yet sold)
Realized Gains: Actual profits/losses (sold assets)
Cost Basis: Original purchase price
• Gains = (Current Price - Purchase Price) × Quantity
• Only realized gains are taxable
• Track each purchase separately
• Unrealized = (Current - Purchase) × Quantity
• Realized = (Sale Price - Purchase) × Quantity
• Track multiple purchases separately
• Calculating gains without considering quantity
• Confusing realized with unrealized gains
• Not tracking individual purchase costs
You bought 1 BTC at $35,000 in March 2022 and sold it for $45,000 in February 2023. If your long-term capital gains tax rate is 15%, what is your tax liability?
Step 1: Calculate realized gain = Sale Price - Purchase Price
Realized Gain = $45,000 - $35,000 = $10,000
Step 2: Determine holding period = From March 2022 to February 2023 = 11 months
Step 3: Apply appropriate tax rate (since 11 months < 1 year, this is short-term)
Short-term gains are taxed as ordinary income, not the long-term rate of 15%
Assuming ordinary income tax rate of 22%: Tax Liability = $10,000 × 0.22 = $2,200
Therefore, your tax liability is $2,200.
This example highlights the importance of holding period in crypto taxation. Even though the question mentioned a 15% long-term rate, the actual holding period of 11 months qualified as short-term, subjecting the gain to ordinary income tax rates. This demonstrates why the duration of holding matters for tax planning.
Short-Term: Assets held ≤1 year
Long-Term: Assets held >1 year
Ordinary Income Tax: Higher tax rate for short-term gains
• Short-term gains: ≤1 year, taxed as ordinary income
• Long-term gains: >1 year, taxed at lower rates
• Holding period affects tax rate significantly
• Hold for >1 year to qualify for long-term rates
• Track purchase and sale dates precisely
• Consider tax implications before selling
• Misclassifying short-term as long-term gains
• Not tracking exact purchase dates
• Assuming all gains are long-term
You made multiple Bitcoin purchases: 1 BTC at $30,000 (Jan), 1 BTC at $35,000 (Mar), 1 BTC at $40,000 (Jun). If you sell 1 BTC in July at $45,000, which cost basis method would result in the lowest tax liability?
Step 1: Calculate gain for each method:
• FIFO (First In, First Out): $45,000 - $30,000 = $15,000 gain
• LIFO (Last In, First Out): $45,000 - $40,000 = $5,000 gain
• Average Cost: $45,000 - (($30,000+$35,000+$40,000)/3) = $45,000 - $35,000 = $10,000 gain
Step 2: Compare gains - LIFO results in the lowest gain of $5,000
Therefore, LIFO would result in the lowest tax liability.
This demonstrates how different cost basis methods can significantly impact tax liability. In a rising market, LIFO minimizes gains by selling the most recently purchased (highest cost) assets first. FIFO, on the other hand, sells the oldest (lowest cost) assets first, resulting in higher gains. The method chosen can have substantial tax implications.
FIFO: First In, First Out - oldest assets sold first
LIFO: Last In, First Out - newest assets sold first
Average Cost: Average purchase price across all holdings
• Different cost basis methods affect tax liability
• LIFO beneficial in rising markets
• FIFO is default method in many jurisdictions
• LIFO = Lower gains in rising markets
• FIFO = Higher gains in rising markets
• Consult tax advisor for optimal strategy
• Not knowing available cost basis methods
• Assuming FIFO is the only option
• Not considering tax implications of sales order
Which of the following activities would NOT trigger a taxable event in most jurisdictions?
The answer is C) Moving crypto between wallets you own. Transferring crypto between wallets you control is not a taxable event since no sale or exchange occurs. The other options all involve disposal of crypto assets, which creates taxable events. Selling, trading, and receiving crypto as payment all have tax implications.
It's crucial to understand what constitutes a taxable event versus what doesn't. Moving assets between wallets you own is simply a transfer of ownership within your estate, not a sale. However, any transaction that involves disposing of crypto (selling, exchanging, gifting, spending) typically creates a taxable event. This distinction is important for accurate tax reporting.
Taxable Event: Transaction triggering tax liability
Asset Disposal: Selling, exchanging, or gifting crypto
Transfer: Moving between wallets without disposal
• Transfers between owned wallets are non-taxable
• Sales and exchanges create taxable events
• Receiving crypto as income is taxable
• Wallet transfers = No tax event
• Any disposal = Taxable event
• Income = Taxable upon receipt
• Reporting wallet transfers as taxable events
• Forgetting to report crypto-to-crypto trades
• Not recognizing received crypto as taxable income
FAQ
Q: How do I track my crypto gains if I use multiple exchanges?
A: Tracking crypto gains across multiple exchanges requires careful record-keeping:
Manual Method:
- Maintain a spreadsheet with all transactions
- Record: Date, Exchange, Asset, Quantity, Price, Fees
- Track cost basis for each purchase
- Calculate gains/losses for each sale
Software Solutions:
- Use crypto tax software like CoinTracker, ZenLedger
- Import transaction histories from exchanges
- Automated cost basis calculations
- Generate tax reports
Always backup transaction records from each exchange as they may not be available indefinitely.
Q: What's the difference between FIFO and specific identification for crypto taxes?
A: The difference lies in how you determine the cost basis of coins sold:
FIFO (First In, First Out):
- Assumes the oldest coins are sold first
- Default method in many jurisdictions
- Simple but may not optimize tax liability
- Example: If you bought 1 BTC at $30K, then 1 BTC at $40K, FIFO assumes you sold the $30K coin first
Specific Identification:
- You specify which exact coins were sold
- Requires detailed record-keeping
- Allows tax optimization
- Example: You can choose to sell the $40K coin first to minimize gains
Specific identification offers more control over tax outcomes but requires precise tracking of each coin's purchase details.