Debt Snowball Simulator
Eliminate debt • Achieve freedom
Debt Snowball Formula:
Show Calculator\( D_t = D_0 - \sum_{i=1}^{t} P_i \)
Where:
- \( D_t \) = Debt remaining at time t
- \( D_0 \) = Initial debt amount
- \( P_i \) = Payment made in period i
- \( t \) = Time period
For compound interest: \( D_t = D_0(1 + r)^t - \sum_{i=1}^{t} P_i(1 + r)^{t-i} \)
Where r = periodic interest rate
Example: $1,000 debt with $200 monthly payments and 1% monthly interest:
After 1 month: \( D_1 = 1000(1.01) - 200 = \$810 \)
After 2 months: \( D_2 = 810(1.01) - 200 = \$618.10 \)
Continuing this pattern eliminates the debt in 5 months.
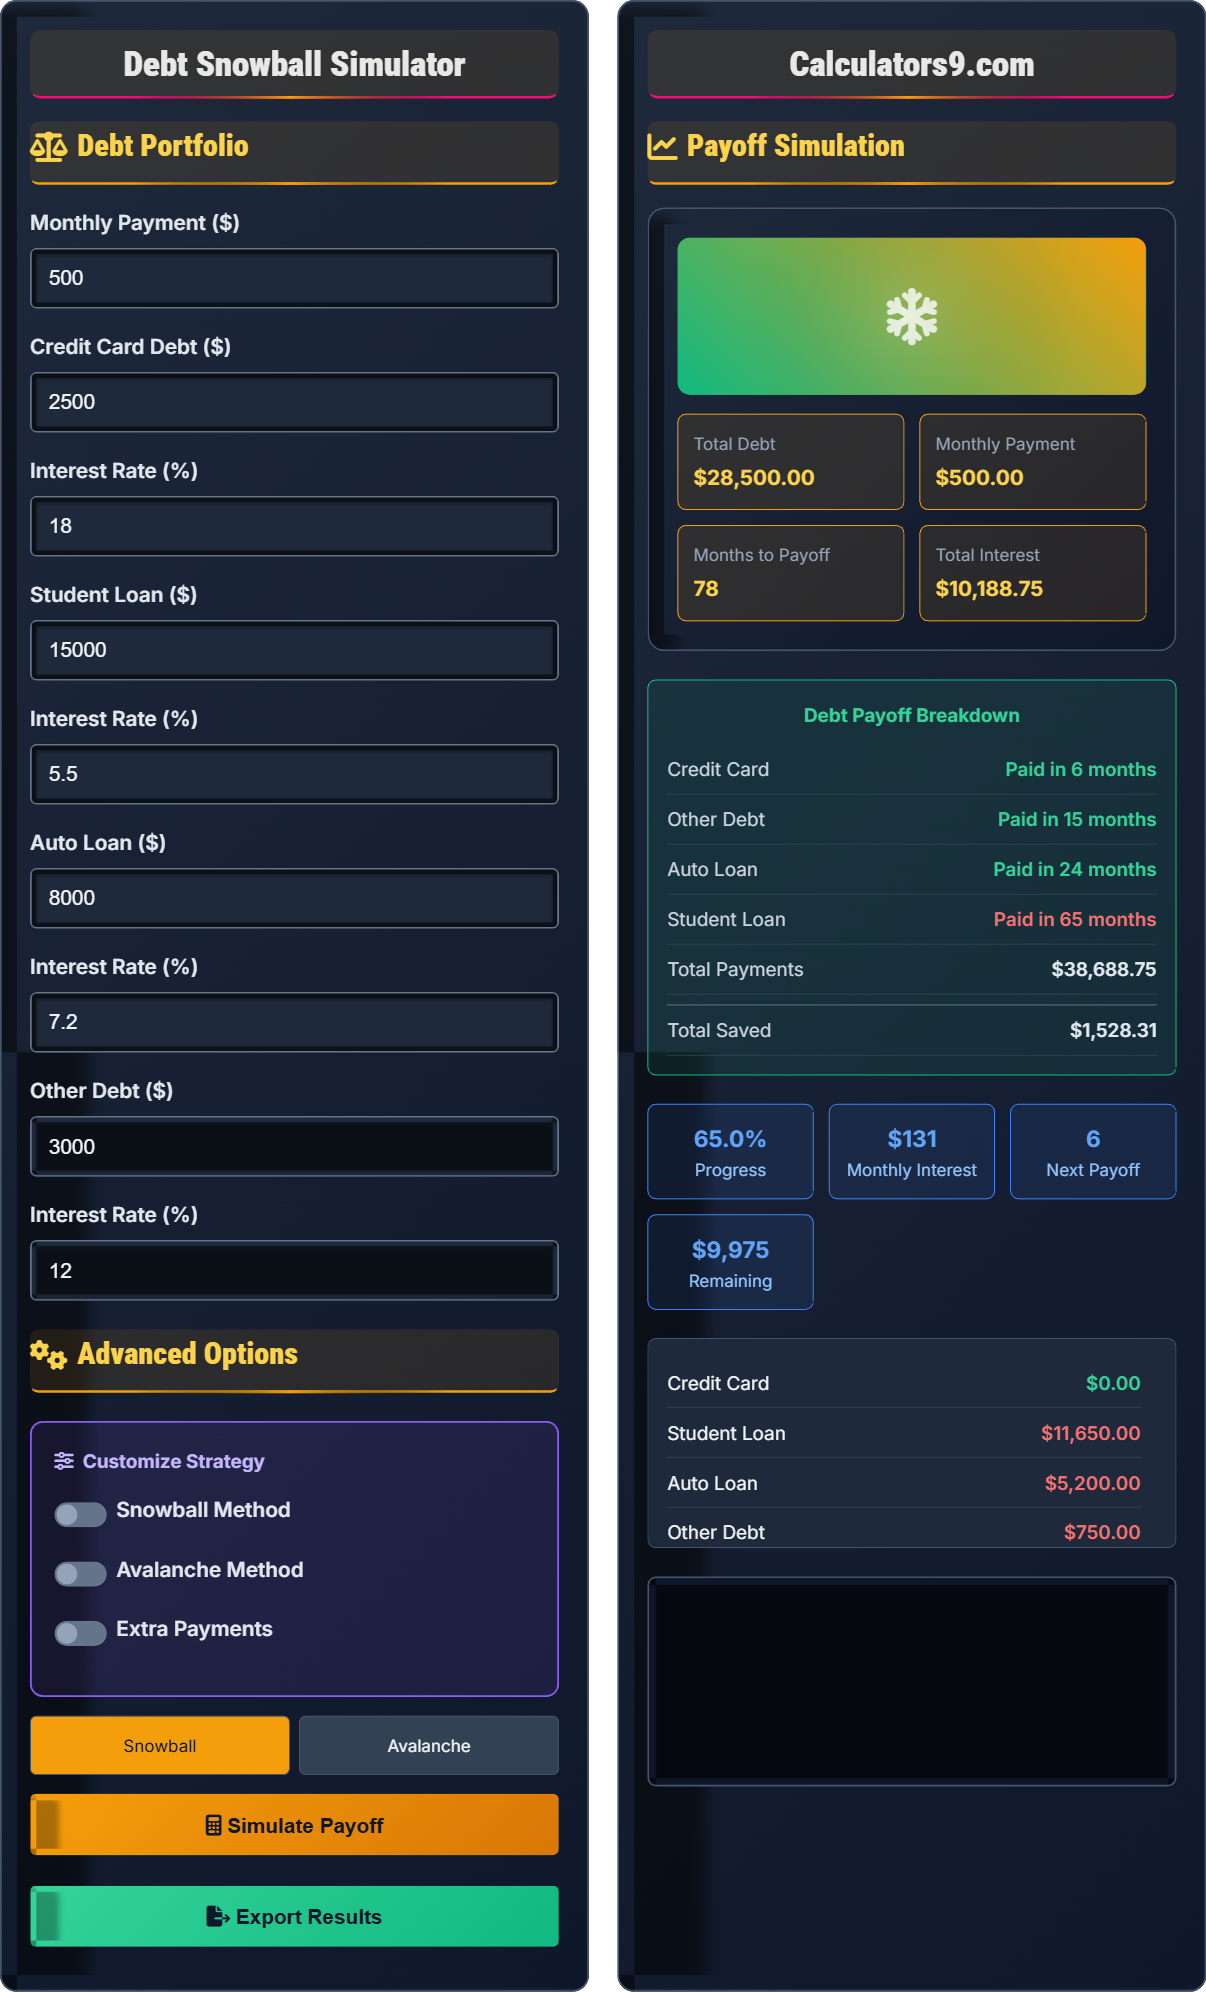
Debt Portfolio
Advanced Options
Payoff Simulation
Debt Elimination Basics
The debt snowball is a debt elimination strategy that focuses on paying off debts from smallest to largest balance, regardless of interest rate.
\(D_t = D_0 - \sum_{i=1}^{t} P_i\)
Where D=debt remaining, P=payment amount, t=time.
- Pay minimums on all debts
- Apply extra to smallest balance
- Roll over payments as debts are paid
- Stay consistent
Strategy Comparison
Snowball focuses on motivation, avalanche focuses on math. Both are effective approaches.
- Snowball: Smallest balance first
- Avalanche: Highest interest first
- Both require minimum payments
- Extra payments accelerate both
- Snowball provides psychological wins
- Avalanche saves more interest
- Personal preference matters
- Combine strategies if needed
Debt Elimination Learning Quiz
What is the primary principle of the debt snowball method?
The answer is B) Pay off smallest balances first. The debt snowball method prioritizes paying off debts from smallest to largest balance, regardless of interest rate. This creates momentum as debts are eliminated one by one, providing psychological wins that motivate continued progress.
The debt snowball method leverages behavioral psychology to create momentum. By targeting the smallest debts first, individuals experience quick wins that build confidence and motivation. This approach recognizes that debt elimination is as much about behavior as it is about mathematics.
Debt Snowball: Pay smallest balances first
Psychological Momentum: Motivation from early wins
Behavioral Finance: Psychology of financial decisions
• Pay minimums on all debts
• Apply extra to smallest balance
• Roll over payments as debts are paid
• List debts from smallest to largest
• Make minimum payments on all
• Put extra toward smallest debt
• Confusing with avalanche method
• Not making minimum payments
• Skipping debts to focus on largest
If someone has a $1,000 debt with 1% monthly interest and makes $200 monthly payments, how much will remain after 3 months? (Hint: Calculate interest and subtract payment each month)
Using the formula: \(D_t = D_0(1 + r)^t - \sum_{i=1}^{t} P_i(1 + r)^{t-i}\)
Month 1: \(D_1 = 1000(1.01) - 200 = 1010 - 200 = \$810\)
Month 2: \(D_2 = 810(1.01) - 200 = 818.10 - 200 = \$618.10\)
Month 3: \(D_3 = 618.10(1.01) - 200 = 624.28 - 200 = \$424.28\)
Therefore, $424.28 will remain after 3 months.
This calculation demonstrates how compound interest affects debt reduction. Each month, interest is applied to the remaining balance before the payment is subtracted. This shows why paying more than the minimum accelerates debt elimination.
Compound Interest: Interest on interest
Monthly Payment: Amount paid each month
Remaining Balance: Debt after payments
• Interest applies before payment
• Minimum payments extend timeline
• Extra payments reduce interest
• Calculate: New Balance = Old Balance × (1 + rate) - Payment
• Pay more than minimum when possible
• Target high-interest debts for savings
• Subtracting payment before adding interest
• Forgetting to compound interest
• Not accounting for partial payments
Sarah has three debts: $500 (credit card), $2,000 (medical bill), and $8,000 (student loan). She can pay $400 monthly toward debt. Using the snowball method, which debt will be paid off first and how long will it take if she pays minimums of $50, $100, and $200 respectively on each?
Step 1: Order debts from smallest to largest: $500, $2,000, $8,000
Step 2: Calculate available extra payment: $400 - $50 - $100 - $200 = $50
Step 3: Apply extra to smallest debt ($500 credit card)
Step 4: Total payment to credit card = $50 + $50 = $100
Step 5: Time to pay $500 debt with $100/month = $500 ÷ $100 = 5 months
Therefore, the credit card debt will be paid off first in 5 months.
This example demonstrates the debt snowball method in action. By focusing on the smallest debt first, Sarah gets her first "win" in 5 months. After that, the $100 payment rolls over to the next smallest debt ($2,000), accelerating its payoff. This creates momentum for tackling the largest debt.
Minimum Payment: Required monthly payment
Extra Payment: Amount above minimum
Payment Roll-over: Applying paid-off payment to next debt
• Make minimum payments on all debts
• Apply extra to smallest balance
• Roll over payments when debt is paid
• List debts smallest to largest
• Calculate total minimum payments
• Apply remainder to smallest debt
• Not making minimum payments on all
• Applying extra to largest debt
• Forgetting to roll over payments
John has two debts: $1,000 at 20% interest and $2,000 at 5% interest. He can pay $300 monthly. Which method (snowball or avalanche) would save him more in interest over time? Calculate the interest savings. (Hint: Snowball pays smaller debt first, avalanche pays higher interest first)
Snowball Method:
Pay minimums: $100 (small debt) + $100 (large debt) = $200
Extra payment: $300 - $200 = $100 to smallest debt
Pay $200 to $1,000 debt: $1,000 ÷ $200 = 5 months
Interest on large debt for 5 months: $2,000 × 0.05/12 × 5 = $41.67
Total interest paid in first phase: $41.67
Avalanche Method:
Pay minimums: $100 (small debt) + $100 (large debt) = $200
Extra payment: $300 - $200 = $100 to highest interest debt
Pay $200 to $2,000 debt: $2,000 ÷ $200 = 10 months
Interest on small debt for 10 months: $1,000 × 0.20/12 × 10 = $166.67
Total interest paid in first phase: $166.67
The avalanche method saves: $166.67 - $41.67 = $125 in interest.
This comparison illustrates the mathematical advantage of the avalanche method. By targeting high-interest debt first, John saves significantly on interest charges. However, the snowball method provides earlier psychological wins. The choice depends on whether saving money or staying motivated is more important.
Interest Savings: Difference in total interest paid
Mathematical Efficiency: Minimizing total interest
Psychological Efficiency: Maintaining motivation
• Avalanche saves more interest
• Snowball provides motivation
• Both require minimum payments
• Use avalanche for maximum savings
• Use snowball for motivation
• Consider hybrid approaches
• Not calculating total interest savings
• Assuming one method fits all
• Ignoring personal preferences
Which of the following is the BEST approach to successfully eliminate debt?
The answer is B) Focus on one debt at a time while maintaining minimums. This approach combines the benefits of debt elimination strategies: making minimum payments prevents defaults while concentrating extra payments accelerates debt elimination. This systematic approach builds momentum and prevents backsliding.
Successful debt elimination requires both discipline and strategy. Making minimum payments maintains good standing with creditors while allowing focus on one debt at a time. This approach prevents the accumulation of late fees and protects credit scores while steadily reducing overall debt burden.
Minimum Payment: Required monthly amount to avoid penalties
Systematic Approach: Consistent, planned method
Debt Elimination: Complete removal of obligations
• Always make minimum payments
• Focus extra payments strategically
• Stay consistent with plan
• Use calendar to track payments
• Celebrate debt elimination milestones
• Avoid taking on new debt
• Missing minimum payments
• Not having a focused strategy
• Accumulating new debt while paying old
FAQ
Q: What's the difference between the debt snowball and avalanche methods?
A: The debt snowball method pays off debts from smallest to largest balance, creating psychological wins. The debt avalanche method pays off debts from highest to lowest interest rate, saving more money in interest.
Snowball: $500 debt → $1,000 debt → $5,000 debt
Avalanche: 20% interest → 15% interest → 5% interest
The formula for debt reduction is: \(D_t = D_0 - \sum_{i=1}^{t} P_i\), where \(D_t\) is debt at time \(t\), \(D_0\) is initial debt, and \(P_i\) is payment in period \(i\).
Q: How do I calculate how long it will take to pay off my debts?
A: For simple calculation without interest: \(T = \frac{D}{P}\), where \(T\) is time, \(D\) is debt amount, and \(P\) is payment amount.
With interest: \(D_t = D_0(1 + r)^t - \sum_{i=1}^{t} P_i(1 + r)^{t-i}\)
For example, $1,000 debt with $200 monthly payments and 1% monthly interest:
- Month 1: $1,000 × 1.01 - $200 = $810
- Month 2: $810 × 1.01 - $200 = $618.10
- Continue until balance reaches $0
This iterative approach gives the exact payoff time.