Monte Carlo Retirement Simulator
Fast retirement planning tool • 2026 metrics
Monte Carlo Formula:
Show the simulator\( V_{t+1} = V_t \times (1 + r_t) - W_t \)
Where:
- \( V_{t+1} \) = Portfolio value at time t+1
- \( V_t \) = Portfolio value at time t
- \( r_t \) = Random return at time t
- \( W_t \) = Withdrawal amount at time t
Monte Carlo simulation repeatedly samples random returns from a probability distribution to model portfolio outcomes:
\( r_t \sim N(\mu, \sigma^2) \)
Where μ is mean return and σ is standard deviation. This formula simulates portfolio evolution with random market returns and systematic withdrawals.
Example: Starting with $1,000,000, withdrawing $40,000 annually (4% rule), with 7% average return and 15% volatility:
The simulation runs thousands of scenarios with different return sequences to calculate the probability of success.
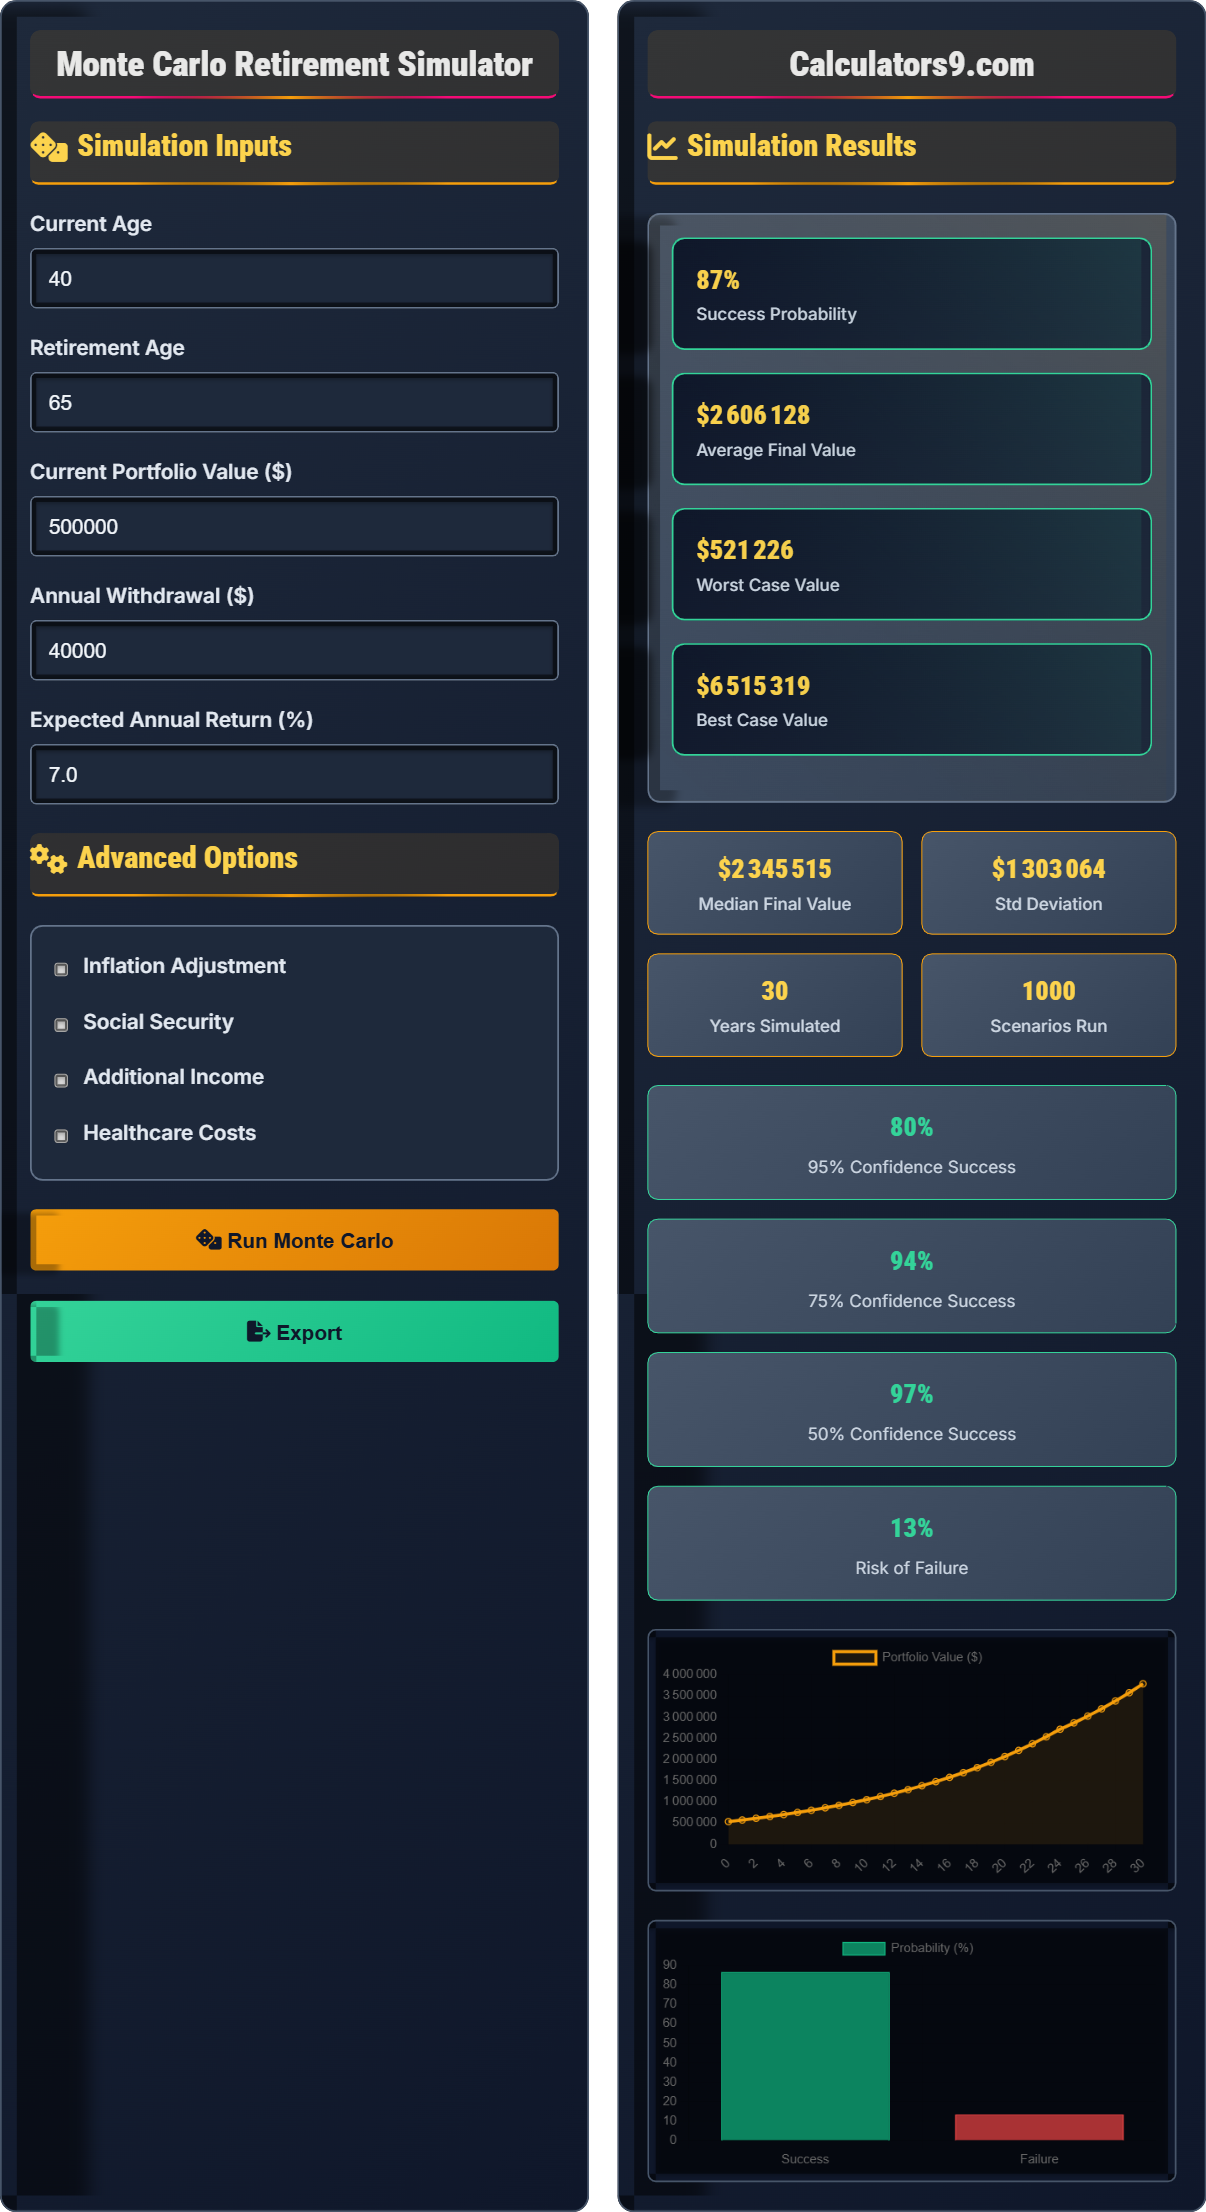
Simulation Inputs
Advanced Options
Simulation Results
Comprehensive Monte Carlo Guide
Monte Carlo simulation is a mathematical technique that uses random sampling to model complex systems and predict outcomes. In retirement planning, it simulates thousands of possible market return sequences to estimate the probability of portfolio success or failure. Instead of relying on a single average return assumption, it accounts for the variability and uncertainty inherent in financial markets.
The fundamental Monte Carlo retirement formula uses the following iterative equation:
Where:
- \(V_{t+1}\) = Portfolio value at time t+1
- \(V_t\) = Portfolio value at time t
- \(r_t\) = Random return at time t
- \(W_t\) = Withdrawal amount at time t
Essential metrics for interpreting Monte Carlo results:
- Success Probability: Percentage of scenarios where portfolio lasts entire retirement
- Confidence Intervals: Ranges where outcomes fall with specified probability
- Expected Value: Average portfolio value across all scenarios
- Median Value: Middle portfolio value when sorted by outcome
- Standard Deviation: Measure of outcome variability
- Withdrawal Rate Testing: Determine safe withdrawal rates with desired success probability
- Scenario Analysis: Test impact of different market conditions
- Asset Allocation: Compare different investment strategies
- Risk Assessment: Quantify probability of portfolio depletion
- Planning Flexibility: Model impact of changing retirement age or spending
Monte Carlo Basics
Statistical method using random sampling to model uncertainty.
\( V_{t+1} = V_t \times (1 + r_t) - W_t \)
Where V=portfolio value, r=random return, W=withdrawal amount.
- Accounts for market volatility
- Provides probability estimates
- Requires many iterations
Strategies
Focus on testing different scenarios and withdrawal strategies.
- Test various withdrawal rates
- Model different asset allocations
- Account for sequence of returns risk
- Adjust for inflation and healthcare costs
- Historical data limitations
- Assumptions affect outcomes
- Sequence of returns matters
- Adjust strategies based on results
Monte Carlo Learning Quiz
What is the primary advantage of Monte Carlo simulation over traditional retirement planning methods?
The answer is B) It accounts for market volatility and uncertainty. Monte Carlo simulation uses random sampling to model the range of possible market outcomes, unlike traditional methods that rely on single-point estimates or average returns. This provides a probability distribution of outcomes rather than a deterministic result.
Traditional retirement planning often uses average returns to project future portfolio values, which can be misleading. Monte Carlo simulation captures the reality that market returns vary significantly from year to year. The sequence of returns matters greatly in retirement planning—poor returns early in retirement can severely impact portfolio longevity, which deterministic models fail to capture.
Monte Carlo Simulation: Statistical technique using random sampling
Sequence of Returns Risk: Impact of return timing on portfolio longevity
Probability Distribution: Range of possible outcomes with likelihoods
• Monte Carlo provides probability estimates, not exact results
• Volatility significantly impacts retirement outcomes
• Early poor returns are particularly harmful
• Run thousands of scenarios for reliable results
• Consider both average and median outcomes
• Focus on confidence intervals rather than single estimates
• Interpreting Monte Carlo results as exact predictions
• Ignoring sequence of returns risk
• Using unrealistic return assumptions
A retiree has a $1,000,000 portfolio and withdraws $40,000 annually (4% rule). A Monte Carlo simulation with 1,000 scenarios shows 85% success rate. What does this mean?
In 85% of the simulated scenarios (850 out of 1,000), the portfolio lasted the entire retirement period without being depleted. This means there's an 85% probability that the retiree's portfolio will sustain their withdrawal needs throughout retirement, assuming the underlying assumptions about market returns and volatility are accurate.
Monte Carlo success probability is expressed as a percentage representing how often the portfolio survived in the simulated scenarios. An 85% success rate suggests a relatively robust withdrawal strategy, though it still implies a 15% chance of portfolio failure. This probabilistic approach is more informative than deterministic models that provide only a single outcome.
Success Rate: Percentage of scenarios where portfolio survives
Portfolio Depletion: When portfolio value reaches zeroProbability Estimate: Likelihood of outcome based on simulation
• Success rate is probability, not certainty
• Higher success rates indicate safer strategies
• Results depend on input assumptions
• Aim for 80-95% success rate depending on risk tolerance
• Consider multiple confidence levels (50%, 75%, 95%)
• Adjust withdrawal amounts based on results
• Treating success rate as guarantee of success
• Ignoring the 15% failure risk
• Not adjusting strategy based on results
A Monte Carlo simulation for a retiree shows these results: 90% success rate, average final value of $1.2M, median final value of $800K, and standard deviation of $1.5M. The retiree is concerned that the median is lower than the average. Explain what this means and what it indicates about the distribution of outcomes.
The median being lower than the average ($800K vs $1.2M) indicates a right-skewed distribution of outcomes. This means there are some scenarios with extremely high final values that pull the average up, while most scenarios cluster around the median. The high standard deviation ($1.5M) confirms significant variability in outcomes. The distribution likely has many modest outcomes but some scenarios with very high portfolio values.
When the mean exceeds the median in Monte Carlo results, it indicates positive skewness—the distribution has a long tail of high-value outcomes. This is common in investment returns due to the potential for exceptional market performance over long periods. The retiree should focus on the median as a more representative "typical" outcome, while understanding that some scenarios could be significantly better.
Mean (Average): Sum of all outcomes divided by number of scenarios
Median: Middle value when outcomes are sorted
Skewness: Asymmetry in probability distribution
• Median represents typical outcome better than mean
• Mean can be skewed by extreme outcomes
• Standard deviation measures outcome variability
• Use median for typical expectation
• Consider both mean and median for complete picture
• High standard deviation indicates greater uncertainty
• Confusing mean and median interpretation
• Ignoring distribution shape in results
• Focusing only on average outcome
A Monte Carlo simulation shows that a retiree has an 80% success rate with a 4% withdrawal rate. However, the retiree experienced a 25% portfolio decline in their first year of retirement. Calculate how this affects their probability of success, and explain why the sequence of returns matters so much in early retirement.
Starting with a 25% decline reduces the portfolio from $1,000,000 to $750,000. If the withdrawal amount remains fixed at $40,000, the withdrawal rate effectively increases from 4% to 5.33% ($40,000 ÷ $750,000). This higher withdrawal rate on a smaller portfolio significantly reduces the probability of success. The sequence matters because early losses occur when the portfolio is largest, and withdrawals represent a larger percentage of the reduced portfolio value.
Sequence of returns risk is the phenomenon where the timing of investment returns significantly impacts portfolio longevity. Poor returns early in retirement are particularly damaging because: 1) They reduce the portfolio when withdrawals are largest as a percentage of portfolio value, 2) There's less time for recovery, and 3) The retiree continues to withdraw from a smaller base. This is why Monte Carlo simulation is valuable—it captures this risk.
Sequence of Returns Risk: Impact of return timing on portfolio longevity
Portfolio Rebalancing: Adjusting allocation after market movements
Withdrawal Rate: Annual withdrawal as percentage of portfolio
• Early poor returns are most damaging
• Withdrawal rate increases with portfolio decline
• Less time for recovery in early retirement
• Consider flexible withdrawal strategies
• Maintain emergency reserves
• Use Monte Carlo to test different scenarios
• Not accounting for sequence of returns risk
• Maintaining fixed withdrawals after market decline
• Ignoring the impact of early market volatility
Which of the following is NOT a typical assumption in Monte Carlo retirement simulations?
The answer is C) Markets exhibit mean reversion. Standard Monte Carlo simulations typically assume returns are independent and identically distributed (IID), often following a normal distribution. Mean reversion implies that returns tend to revert to their long-term average over time, which contradicts the IID assumption. While some advanced models incorporate mean reversion, it's not a standard assumption in basic Monte Carlo simulations.
Monte Carlo simulations make simplifying assumptions to make the math tractable. The IID assumption means each year's return is independent of previous years, which may not reflect real-world market behavior where trends and mean reversion can occur. Understanding these assumptions helps interpret results appropriately and recognize the limitations of the model.
IID: Independent and identically distributed
Mean Reversion: Tendency to return to long-term averageNormal Distribution: Bell-shaped probability distribution
• Standard MC assumes IID returns
• Normal distribution is common assumption
• Assumptions limit model accuracy
• Understand model assumptions
• Consider multiple modeling approaches
• Use results as guides, not guarantees
• Treating model assumptions as market facts
• Ignoring model limitations
• Not validating assumptions with historical data
FAQ
Q: How many Monte Carlo simulations should I run for reliable results?
A: For reliable Monte Carlo results, run at least 1,000 to 10,000 simulations:
- 1,000 simulations: Minimum for stable probability estimates
- 5,000-10,000: Recommended for accurate confidence intervals
- More than 10,000: Marginal improvement in accuracy
Running too few simulations can lead to unstable results due to random sampling variation. However, the law of diminishing returns applies—beyond 10,000 simulations, the improvement in accuracy is minimal compared to computational cost.
Q: Should I adjust my withdrawal strategy based on Monte Carlo results?
A: Yes, Monte Carlo results should inform your withdrawal strategy:
- Low success rate (<80%): Reduce withdrawal amount or delay retirement
- High success rate (>95%): Consider slightly higher withdrawals
- Medium success rate (80-95%): Implement flexible withdrawal rules
Consider implementing dynamic withdrawal strategies that adjust based on portfolio performance. For example, temporarily reduce withdrawals after significant market declines, or increase withdrawals if the portfolio significantly outperforms expectations.