Gift Tax Calculator
Fast gift tax calculator • 2026 rates
Gift Tax Formula:
Show the calculator\( GT = \max(0, (TG - AE - LE) \times TR) \)
Where:
- \( GT \) = Gift Tax Owed
- \( TG \) = Total Gifts (over annual exclusion)
- \( AE \) = Annual Exclusion ($18,000 per recipient in 2026)
- \( LE \) = Lifetime Exemption ($13,610,000 in 2026)
- \( TR \) = Tax Rate (18-40%)
Alternative formulas:
\( AG = \min(AE, G) \)
\( TE = LE - ULE \)
This formula calculates gift tax based on total gifts exceeding annual exclusions and lifetime exemptions.
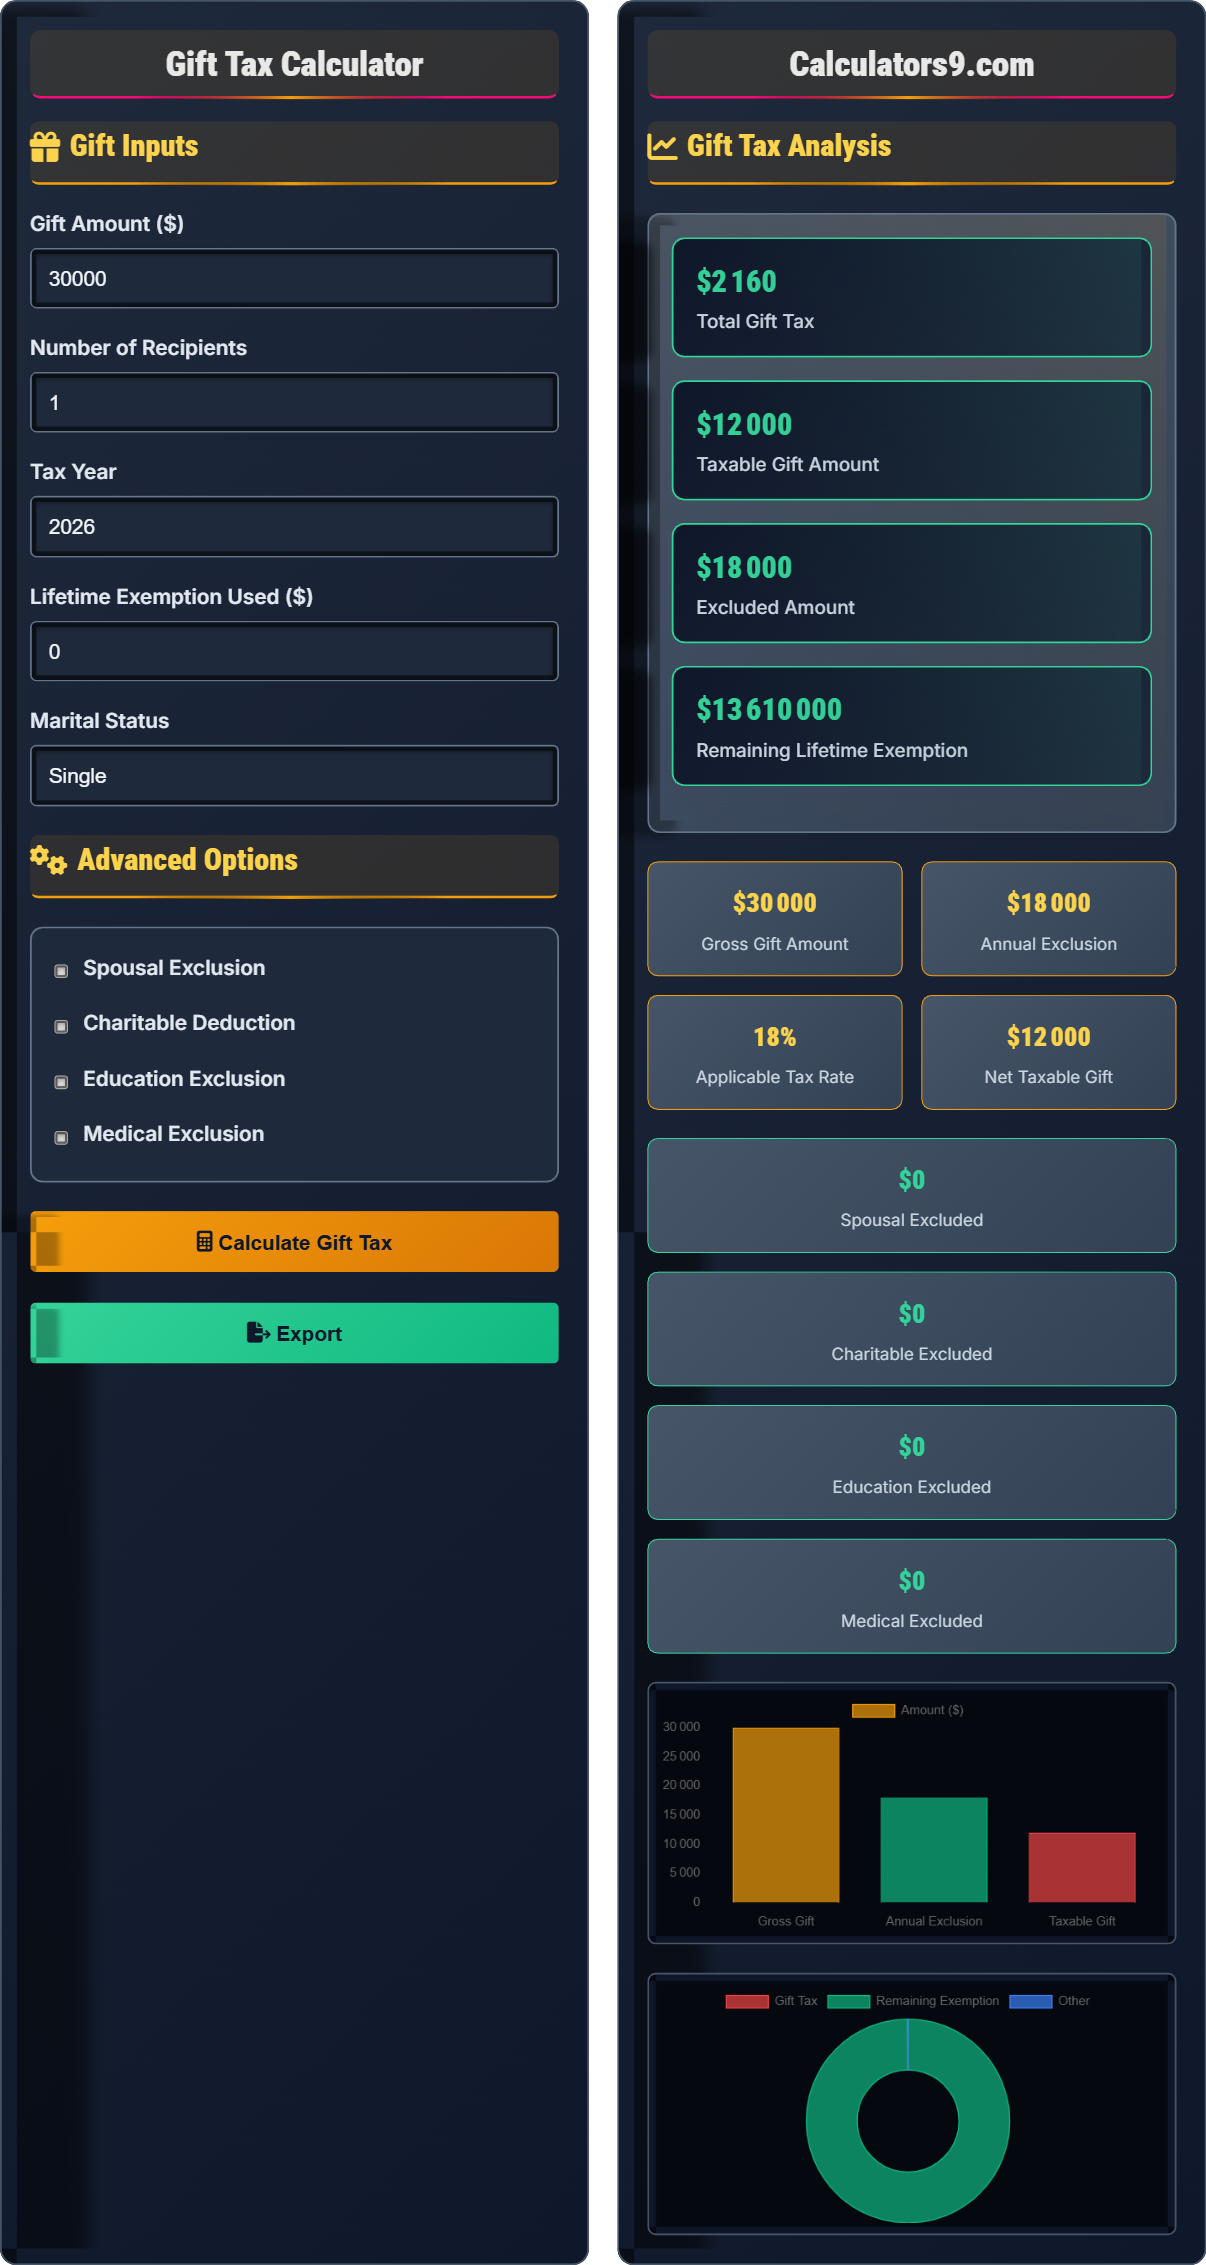
Example: Giving $30,000 to one person in 2026:
Excluded amount = $18,000
Taxable amount = $30,000 - $18,000 = $12,000
Gift tax = $12,000 × applicable rate (usually 18% for first bracket) = $2,160
Gift Inputs
Advanced Options
Gift Tax Analysis
Comprehensive Gift Tax Guide
Gift tax is a federal tax imposed on the transfer of property or money from one person to another without receiving equal value in return. The tax is typically paid by the donor (person making the gift), not the recipient. Gift tax is part of the unified transfer tax system that includes estate tax and generation-skipping transfer tax.
The fundamental gift tax calculation uses the following formula:
Where:
- \(GT\) = Gift Tax
- \(TG\) = Total Gifts
- \(AE\) = Annual Exclusion
- \(LE\) = Lifetime Exemption
- \(TR\) = Tax Rate
Gift tax rates follow a progressive schedule:
- 18%: First $10,000 of taxable gifts
- 20%: Next $10,000 of taxable gifts
- 22%: Next $20,000 of taxable gifts
- 24%: Next $40,000 of taxable gifts
- 26%: Next $40,000 of taxable gifts
- 28%: Next $50,000 of taxable gifts
- 30%: Next $100,000 of taxable gifts
- 32%: Next $100,000 of taxable gifts
- 34%: Next $100,000 of taxable gifts
- 37%: Next $100,000 of taxable gifts
- 39%: Next $100,000 of taxable gifts
- 40%: Any remaining taxable gifts
- Annual Exclusion Maximization: Take advantage of annual exclusions each year
- Generation Skipping: Use GST exemption for grandchild gifts
- Charitable Gifting: Reduce taxable estate through charitable gifts
- Life Insurance Trusts: Remove assets from taxable estate
- Family Limited Partnerships: Discount valuation for gift tax purposes
Gift Tax Basics
Federal tax on transfers of property without receiving equal value.
\( GT = \max(0, (TG - AE - LE) \times TR) \)
Where GT=gift tax, TG=total gifts, AE=annual exclusion, LE=lifetime exemption, TR=tax rate.
- Donor pays the tax
- Annual exclusion of $18,000
- Lifetime exemption of $13.61M
Strategies
Focus on maximizing exclusions and minimizing tax.
- Use annual exclusion each year
- Consider charitable gifting
- Plan for education/medical payments
- Utilize spousal exclusions
- Annual exclusions reset each year
- Lifetime exemption is shared with estate tax
- Gift tax is progressive
- Direct payments have special rules
Gift Tax Learning Quiz
Who is responsible for paying gift tax?
The answer is B) The donor (person making the gift). According to IRS regulations, the donor is responsible for filing Form 709 and paying any gift tax owed. However, in practice, the recipient may agree to pay the tax if both parties consent, but legally the responsibility lies with the donor.
This is a fundamental principle of gift tax law that many people find counterintuitive. The person receiving the gift doesn't pay tax on the gift itself (though they may owe income tax on certain types of gifts), but rather the person making the gift is responsible for any tax consequences. This is different from income tax, where the recipient typically owes tax.
Donor: Person making the gift
Recipient: Person receiving the gift
Form 709: Federal gift tax return
• Donor is responsible for gift tax
• Recipient doesn't pay tax on gift
• Donor files Form 709 if required
• Remember: Donor pays gift tax
• Recipient gets gift tax-free
• Donor must file if gift exceeds annual exclusion
• Thinking recipient pays gift tax
• Confusing gift tax with income tax
• Not understanding filing requirements
If you give $25,000 to one person in 2026, how much of that gift is subject to gift tax (ignoring lifetime exemption)?
Using the gift tax formula: \( TG = \max(0, G - AE) \)
Given:
- Gift Amount = $25,000
- Annual Exclusion (2026) = $18,000
Step 1: Subtract annual exclusion from gift = $25,000 - $18,000 = $7,000
Step 2: Taxable gift amount = $7,000 (since it's positive)
Therefore, $7,000 of the gift is subject to gift tax.
This calculation shows how the annual exclusion works to reduce the taxable portion of gifts. The annual exclusion acts as a tax-free allowance for gifts each year. Any amount above the exclusion is potentially subject to gift tax, though the actual tax may be offset by the unified credit.
Annual Exclusion: Tax-free allowance per recipient per year
Taxable Gift: Amount subject to gift tax
Unified Credit: Credit against gift tax liability
• Annual exclusion reduces taxable gift
• Exclusion is per recipient per year
• Excess over exclusion may be taxable
• Annual exclusion is $18,000 per recipient in 2026
• Forgetting to subtract annual exclusion
• Not knowing current annual exclusion amount
• Confusing annual exclusion with lifetime exemption
A married couple wants to give $50,000 to their child in 2026. If they elect to split the gift, how much of the gift would be subject to gift tax? What if they don't split the gift?
With gift splitting:
Each spouse is deemed to give $25,000
Annual exclusion per spouse = $18,000
Taxable amount per spouse = $25,000 - $18,000 = $7,000
Total taxable = $7,000 × 2 = $14,000
Without gift splitting:
One spouse gives entire $50,000
Taxable amount = $50,000 - $18,000 = $32,000
With gift splitting, $14,000 is taxable. Without splitting, $32,000 is taxable.
Gift splitting allows married couples to effectively double their annual exclusion for gifts to the same person. This is a powerful tax planning strategy that can significantly reduce gift tax liability. The couple must elect to split gifts by filing Form 709, even if no tax is otherwise due.
Gift Splitting: Election to treat gifts as made half by each spouse
Annual Exclusion: Tax-free allowance per person per year
Form 709: Required filing for gift splitting
• Gift splitting doubles effective annual exclusion
• Requires filing Form 709
• Must be elected by both spouses
• Gift splitting is beneficial for large gifts
• Both spouses must consent to splitting
• File Form 709 to elect splitting
• Forgetting to file Form 709 for gift splitting
• Not understanding the benefits of gift splitting
• Assuming gift splitting happens automatically
A parent wants to pay $30,000 in college tuition and give $15,000 in cash to their child in 2026. What is the total gift tax liability? What if they gave the entire $45,000 as cash instead?
With education payment:
Direct tuition payment = $30,000 (excluded from gift tax)
Cash gift = $15,000
Annual exclusion = $18,000
Taxable gift = $15,000 - $18,000 = $0 (no tax due)
Total gift tax = $0
If entire $45,000 given as cash:
Taxable gift = $45,000 - $18,000 = $27,000
Gift tax = $27,000 × 18% = $4,860 (first bracket)
By using the education exclusion, the parent saves $4,860 in gift tax.
This demonstrates the significant tax savings possible through proper use of exclusions. Payments made directly to educational institutions for tuition are completely excluded from gift tax, while cash gifts are subject to the annual exclusion. This is a valuable strategy for funding education while minimizing tax impact.
Education Exclusion: Direct tuition payments are excluded
Medical Exclusion: Direct medical payments are excluded
Annual Exclusion: Standard tax-free allowance
• Direct education payments are excluded
• Must pay institution directly
• No limit on exclusion amount
• Pay tuition directly to school to avoid gift tax
• Same applies to medical bills
• Combine with annual exclusion for maximum benefit
• Giving cash instead of paying institution directly
• Not understanding education exclusion benefits
• Confusing qualified expenses for exclusions
How does the unified credit affect gift tax liability?
The answer is B) It reduces or eliminates gift tax on gifts within the lifetime exemption. The unified credit is essentially a tax credit that offsets gift tax liability on taxable gifts up to the lifetime exemption amount. It's called "unified" because it applies to both gift tax and estate tax.
The unified credit is a crucial component of the gift and estate tax system. It functions as a dollar-for-dollar reduction in tax liability, effectively allowing individuals to make gifts up to the lifetime exemption amount without paying actual gift tax. However, making taxable gifts reduces the amount of the lifetime exemption available for estate tax purposes.
Unified Credit: Tax credit against gift/estate tax
Lifetime Exemption: Amount that can be gifted tax-freeUnified System: Link between gift and estate taxes
• Unified credit reduces gift tax liability
• Applies to both gift and estate tax
• Reduces available estate tax exemption
• Understand the unified system
• Large gifts reduce estate tax exemption
• Plan for both gift and estate tax together
• Not understanding unified credit function
• Thinking gift and estate taxes are separate
• Not considering estate tax impact of gifts
FAQ
Q: Do I need to file a gift tax return if I give more than the annual exclusion?
A: Yes, you must file Form 709 if you give gifts that exceed the annual exclusion amount ($18,000 in 2026) to any one person, even if no tax is actually owed due to the unified credit. The filing requirement is triggered by exceeding the annual exclusion, not by owing tax.
However, you don't need to file if the gift qualifies for an exclusion (such as direct payments for tuition or medical expenses) or if it's to your spouse (for U.S. citizen spouses).
Q: How does gift tax interact with estate tax?
A: Gift tax and estate tax are unified under the "unified credit" system:
- Shared Exemption: The same lifetime exemption ($13.61M in 2026) applies to both gift tax and estate tax
- Tax Credit: The unified credit reduces both gift tax and estate tax liability
- Coordination: Making taxable gifts during life reduces the estate tax exemption available at death
This means that gifts that use up part of your lifetime exemption during life will reduce the amount of assets that can pass tax-free at your death.